Before something happens
Build the record you'll be glad you have.
Evaluu helps you document what you own — it is not insurance, legal or financial advice, and does not guarantee any claim outcome.
A fair, dated inventory of what you actually own — built one scan at a time, on a normal weekend, while nothing's gone wrong. So when something does, the conversation with the adjuster is short and you keep what you should.
• Inventory live today
• Insurance printout
• No credit card
The moment you're avoiding
The hardest call to make is the one to your adjuster.
"Do you have photos? Receipts? Any record of what was in the room?"
That's the question. And almost nobody has a real answer. Your stuff is in your head — the couch you bought five years ago, the bike in the garage, the camera you got for a birthday. Without a record, every claim becomes a negotiation. Without a record, the payout reflects what you can remember, not what you actually owned.
The fix isn't dramatic. It's a quiet weekend, a phone in your hand, and one room at a time. Evaluu does the valuing. You do the walking.
The inventory lives today. The formal printout for your insurer is coming soon — and when it ships, your inventory rolls into it automatically.
What you walk away with
A record that doesn't depend on memory.
Every item dated, identified, valued at current market.
Receipt photos and warranty cards attached to the right items.
Values that refresh as the market changes — no more "I think it was $1,200 at the time."
A clean export when the printout ships Coming soon — for your insurer, your renter's or homeowner's policy, and any scheduled-item riders.
What people miss
The claims people regret are the ones for items they didn't think to document.
Adjusters aren't trying to lowball you. They just can't pay for what you can't prove you owned.
The receipts no one kept.
The TV, the couch, the espresso machine. Bought years ago, the receipt got recycled, the email's lost. Without one, the depreciated cash payout is a fraction of what you'd actually replace it for.
The items no one photographed.
Art on the wall, jewelry in a drawer, the bike in the garage. If nothing is photographed, nothing exists for the adjuster. Evaluu captures and dates the image when you scan.
The upgrades after you moved in.
Most home inventories are frozen at the day of the policy. The new dishwasher, the recent TV, the home gym you added last year — usually not in the file. Evaluu updates as you do.
The high-ticket gifts.
The watch, the ring, the camera. Items often given without a receipt. Most homeowner's policies sub-limit jewelry and electronics without a scheduled-item rider — and the rider needs documentation Evaluu builds for you.
THREE STEPS
Scan. Document. Update.
Built so the inventory grows quietly in the background of normal life — not in a panic after something happens.
01 — Scan
Walk a room.
Start with the living room. Point your camera at the things that would actually go on a claim — furniture, electronics, art, jewelry, instruments. One pass per room.
A two-bedroom in 45 minutes. A whole house in an unhurried weekend.
02 — Know
Capture the proof.
Each scan saves a dated photo, identification, current market value, and any receipt or warranty you attach. The kind of file an adjuster won't argue with.
Photos, values, dates — all timestamped, all defensible.
03 — DECIDE
Refresh as life changes.
Buy something new, scan it. Replace the couch, swap the entry. Values update automatically against current market data — so your inventory reflects today, not 2019.
Quiet maintenance. Real coverage when it matters.
What you can actually do with it
One inventory. A handful of bad days, eased.
01
File a full-loss claim with a list, not a memory.
Fire. Flood. Total break-in. The worst days are made worse by trying to remember what was in every room. Hand the adjuster a dated, room-by-room inventory and the conversation gets short — and your payout reflects what you actually owned.
Total loss · Catastrophic
02
Resolve partial-loss claims faster.
The pipe burst in the basement, the storm took the patio, the laptop fell off the counter. Smaller claims close faster when you can show what was there, what it was worth, and what it'd cost to replace.
Partial loss · Daily
03
Get the scheduled-item rider right.
Standard homeowner's policies cap jewelry, watches, electronics, and art at low sub-limits. The rider that fixes it requires documentation — descriptions, photos, values. Evaluu builds the file you'll attach to the policy.
Rider · Scheduled items
04
Hand your renter's or homeowner's insurer a real number.
Most people guess at their personal-property coverage limit. "Maybe $30,000?" Almost everyone is under-insured by a meaningful amount. A real inventory gives you the actual number — and a reason to call your agent about coverage that matches.
Renew · Coverage
05
Cover the gap when things are in motion.
Moves, storage, a household in transition between policies. The window between coverages is where things get lost. A current inventory lets you bridge it cleanly.
In transit · Storage
Questions people ask first
One clean document. Built from the inventory you're already making.
"What an adjuster wants on day one — and what your insurer asks for when a rider goes on the policy."
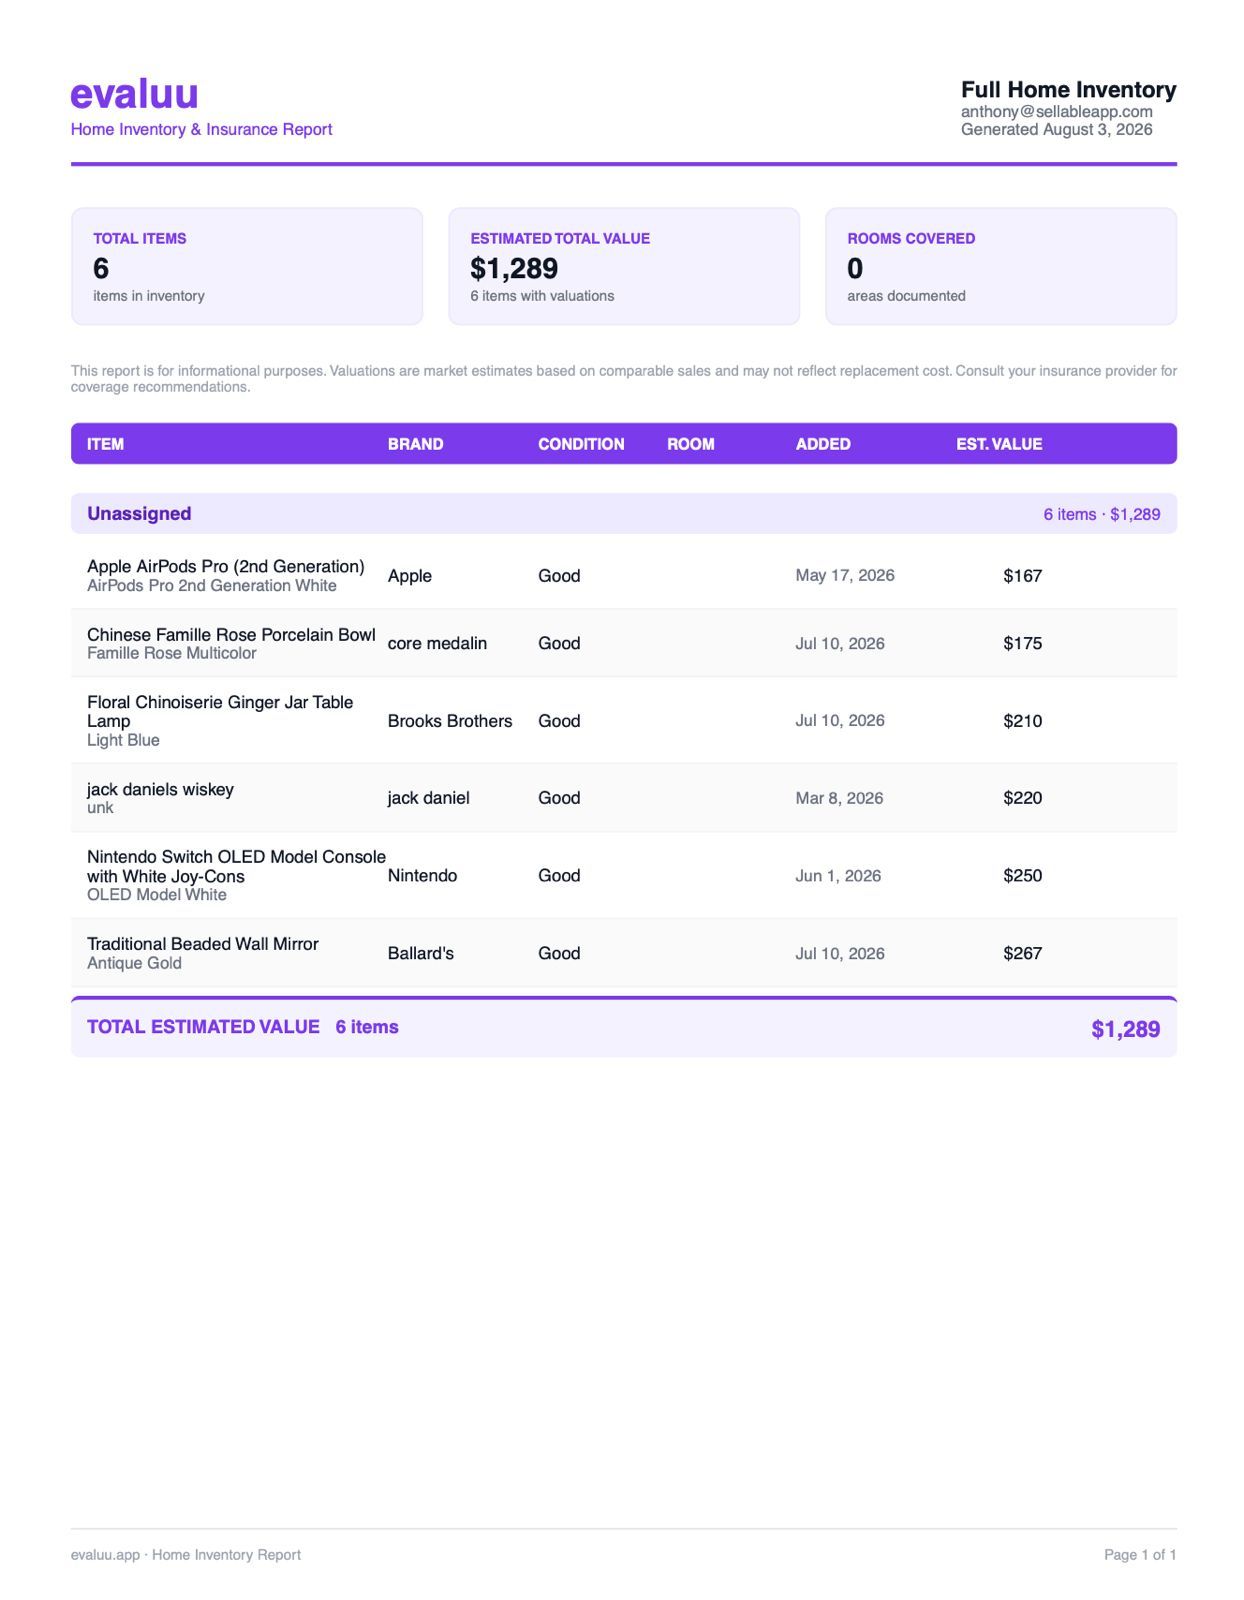
The Insurance Report is a single, lawyer- and adjuster-friendly PDF generated from your Evaluu inventory. It lists every item room-by-room with description, identification, current market value, condition factors, photos, and a timestamp. Add receipts and warranties where you've got them. Export when you need it.
The inventory is live today. The printout ships next. Start your inventory now and it'll roll into the report automatically when it's released — no rework, no re-scanning.
Room-by-room itemization with photos and dated values.
A clean per-room and home-total summary on the cover page.
Source citations and methodology notes on every value.
Optional scheduled-item appendix for jewelry, art, and electronics riders.
Questions people ask first
What you're
probably
wondering.
If something here doesn't answer your question, write to us. We read every message and most weeks reply within a few hours.
"The boring weekend that pays for itself the day it matters."
When does the insurance-ready printout ship?
Soon. The inventory features — scanning, identification, valuation, photos, room tagging — are live today. The formal Insurance Report PDF (cover page, room-by-room itemization, source citations, scheduled-item appendix) is in active development and ships next. Anything you build into your inventory now rolls into the report automatically when it's released. No re-scanning, no rework.
How long does it take to build a full home inventory?
A two-bedroom apartment, comfortably in 45–90 minutes. A four-bedroom house, an unhurried weekend. Most people work room by room over a few sessions. The point is to start — even one room is more than most households have today.
Will my insurance company accept this as a home inventory?
Most insurers ask for what Evaluu produces: a dated list of items with descriptions, photos, and values. Industry-standard requirements vary — some carriers want appraisals on individual high-value items above a threshold (typically jewelry over $5,000 or art over a stated limit). For those items, Evaluu flags them and recommends a formal appraisal in addition to the inventory.
Does it work for renters too?
Yes. Renter's insurance covers personal property the same way homeowner's does — and most renters carry significantly less coverage than their belongings are actually worth. An Evaluu inventory tells you the real number, so the policy limit can match it.
What about receipts I don't have anymore?
Most people don't have receipts for things bought more than a year or two ago. That's fine — Evaluu generates a current market value from comps regardless of whether a receipt is attached. Attach what you have, scan everything else, and the values come from the market either way.
Is the inventory private?
Yes. Your inventory is private to your account. It's only shared when you choose to export it — to your insurance agent, to an adjuster, to yourself for records. Nothing is shared with anyone by default.
Is it free?
Get started free — scan, value, photograph, and tag items at no cost. Multi-property inventories, scheduled-item appendices, and the Insurance Report export (when it ships) are part of our paid tier. You can decide once you've used it.
Start with one box
Build it now. Be glad you did later.
Make an account, scan the room around you, and start a quiet inventory you'll be relieved to have if the day ever comes. The insurance printout ships next — your work now rolls into it automatically.
• Inventory live today
• Insurance printout
• No credit card